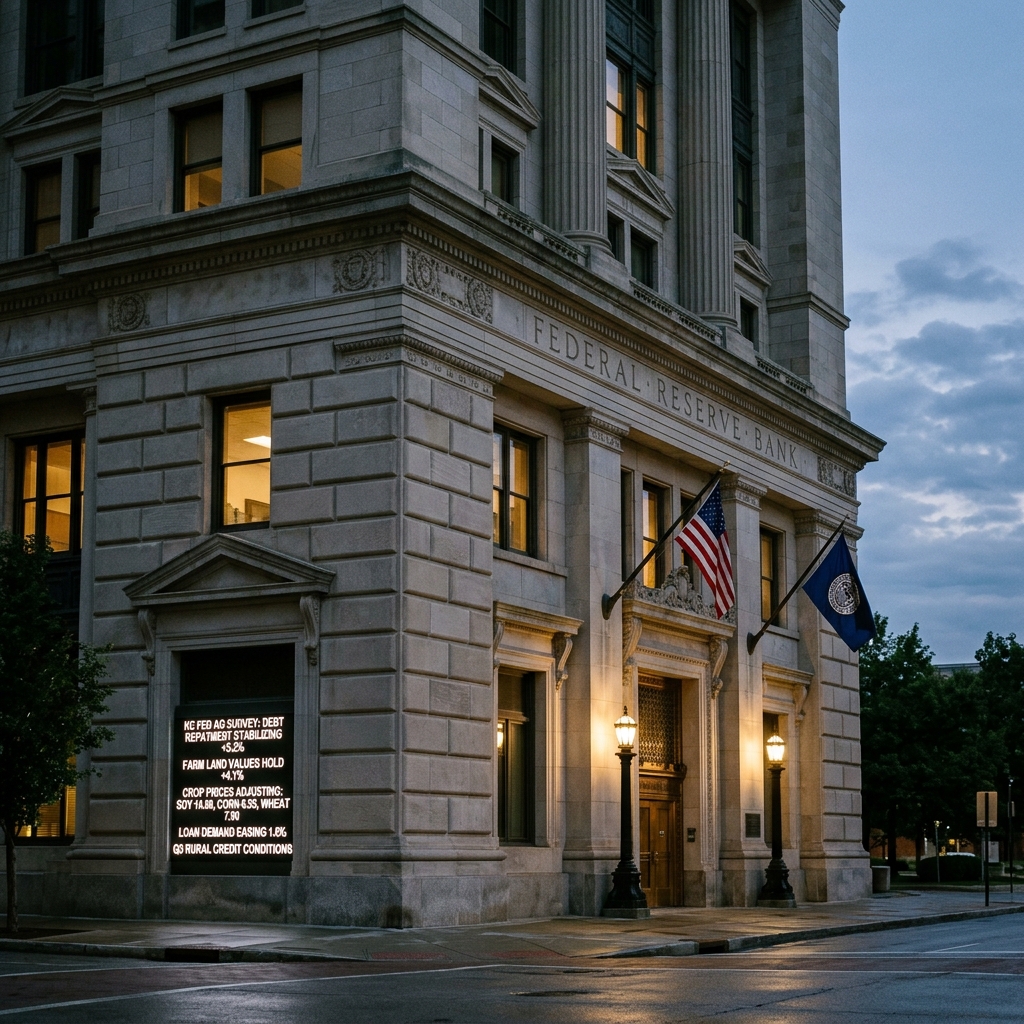
1. Tenth District Survey Signals Relief on Agricultural Loan Portfolios
The Federal Reserve Bank of Kansas City reported this week that the liquidity squeeze on Midwest farm operations is beginning to stabilize. According to its latest Agricultural Credit Survey, farm income remains well below the peaks seen in 2022, yet the deterioration of debt service capacity slowed noticeably in the fourth quarter. Agricultural bankers across western Missouri, Kansas, Nebraska, Oklahoma, Colorado, northern New Mexico, and Wyoming noted fewer requests for emergency credit line extensions than expected six months ago.
Steady repayment rates on non-real estate farm loans helped drive this improvement. Delinquency rates at commercial agricultural banks across the district stayed below historical averages, backed by strong collateral values on deeded cropland. Economists at the Kansas City Fed pointed out that while overall production expenses remain high, wholesale prices for nitrogen-based fertilizers and diesel fell between 14% and 22% year-over-year. That decrease delivered immediate relief to cash-crop growers securing operating lines for spring planting.
Lenders are sticking to firm loan-to-value caps, which has kept credit from contracting sharply. Interest rates on operating lines hovered near 8.5%, prompting growers to trim discretionary borrowing and put off equipment purchases. Many producers chose to pay down existing variable-rate debt instead of taking out loans for new combines or storage facilities. That conservative approach preserved cash, allowing operations to manage volatile commodity prices without causing broad distress for regional agricultural lenders.
2. Working Capital Adjustments Reshape Farm Machinery and Input Demand
These financial adjustments are visible across local farm supply chains. Dealerships across the grain belt are carrying larger inventories of high-horsepower tractors and combines, prompting manufacturers to discount select models. Rather than financing new equipment at rates tied to prime, farmers are running existing fleets longer. Postponing replacements helped protect working capital reserves that took a hit during the 2023 rate increases.
Farmland values continue to support farm balance sheets across the Tenth District. Non-irrigated land prices held steady, posting modest annual gains between 2% and 4% in Kansas and Nebraska despite elevated capitalization rates. Bankers reported that bidding at auctions remained active, supported by cash reserves from institutional investors and neighboring operators looking to expand. This stability in real estate values has prevented the collateral erosion that marked the farm debt crisis of the 1980s.
Community banks are keeping underwriting tight. Fed survey data shows that loan officers are applying stricter stress tests to borrower cash-flow projections. Operations must show positive returns at five-dollar corn and eleven-dollar soybeans before securing revolving credit lines. By setting these benchmarks early, lenders pushed operators to cut spending ahead of time, heading off liquidity shortfalls and forced asset sales.
3. Cross-Border Supply Chains and the CPKC Freight Arteries
Finances for Tenth District growers remain closely tied to trade between the United States and Canada. The Canadian Pacific Kansas City (CPKC) rail network moves Saskatchewan potash straight to grain operations in Iowa, Missouri, and Kansas. Normalized rail performance and fewer bulk transport disruptions helped lower delivered input costs for American producers. This steady supply chain cut thousands of dollars in variable expenses per section during late-fall fertilizer applications.
At the same time, two-way trade in feeder cattle and processed meats through border crossings such as Coutts, Alberta, and Sweet Grass, Montana, delivered essential revenue to northern plains ranchers. Strong demand from Canadian packers, combined with smaller cattle inventories in the southern plains, kept live cattle prices firm. Data from the U.S. Department of Agriculture and the Canadian Food Inspection Agency shows cross-border livestock shipments held steady, giving producers enough operating margin to service bank debt.
The terms of the United States-Mexico-Canada Agreement (USMCA) continue to shield these corridors from unexpected tariff changes. While phytosanitary inspections run by U.S. Customs and Border Protection (CBP) and the Canada Border Services Agency (CBSA) require ongoing administrative work, rail traffic moved without substantial border hold-ups. Reliable logistics enabled elevators and commercial feedlots to fulfill contracts without late penalties, supporting cash flow on both sides of the border.
4. Central Bank Divergence and Cross-Border Farm Capitalization
Agricultural finances must now contend with diverging monetary policy between the Federal Reserve and the Bank of Canada. As the Bank of Canada cut interest rates faster than the Fed, the Canadian dollar weakened against the U.S. dollar. The lower exchange rate makes Canadian inputs and processing equipment more affordable for American buyers, but it raises the cost of U.S.-made machinery parts and specialty seed for producers in Ontario and the Prairie provinces.
For agribusinesses running grain terminals along the Great Lakes and northern rail routes, currency movements require steady hedging through the Chicago Mercantile Exchange. Handlers must manage both commodity price shifts and the Canadian-U.S. dollar exchange rate to lock in processing margins. Kansas City Fed data indicates that disciplined hedging has allowed firms to handle these spreads, using dependable export business to cover dollar-denominated debt without overextending commercial credit lines.
Looking ahead, farm balance sheets will depend more on crop prices and trade flows than on a sudden pullback in credit. If the Federal Reserve moves slowly on further rate cuts, borrowing costs will stay well above the levels seen over the past decade. Even so, the Kansas City Fed report shows that growers have adjusted to higher debt expenses by curbing capital outlays, keeping debt levels manageable, and utilizing established cross-border supply lines.